


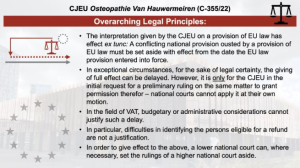
Where EU law rights are fiscally inconvenient, Member States may sometimes try to delay their implementation. In particular, they might attempt to refuse refunds of unduly charged VAT, to their own enrichment and the detriment of businesses. Gladly, the Court shows little mercy with such attempts. This is not generous, but plainly necessary: Had it been otherwise, Member States might impose taxes in breach of EU law, knowing full well that they can get away with it for a few years before being challenged.
Source Fabian Barth
See also
- Join the Linkedin Group on ECJ VAT Cases, click HERE
- VATupdate.com – Your FREE source of information on ECJ VAT Cases
Latest Posts in "European Union"
- Commission to grant temporary trade preferences to support Armenian exports to the EU
- EPPO Dismantles €410 Million VAT Fraud Ring in Eight-Country Raids
- Comments on T-773/25: EU Court Rules Late Reverse-Charge Wording Does Not Retroactively Activate Triangulation Simplification
- No Reverse Charge, No Triangulation Relief: Late Invoice Fix Fails
- BFH Refers Automated Plant Permanent Establishment Question to EU Court












